The Alumni Association account that collects all your donations had approximately $28,523 in cash on hand as of May 31. Our total expenses for the year were $102,834, with $43,480 being spent on direct support for the active chapter, $36,842 to subsidize the operating costs of the Housing Corp, and the remainder spent on reunions, Alumni Association services, and other miscellaneous items (mostly Delta chapter-specific décor for the house). This was an expensive year, but it was also a transitional year and most of these costs were necessary and expected, which is why we intentionally ran a large surplus the prior year in preparation for these large outlays. The effects of our active chapter assistance are apparent in both the number and high moral character of the Spring 2026 pledge class. With the active chapter nearing full strength, we expect they will need less financial aid from alumni.
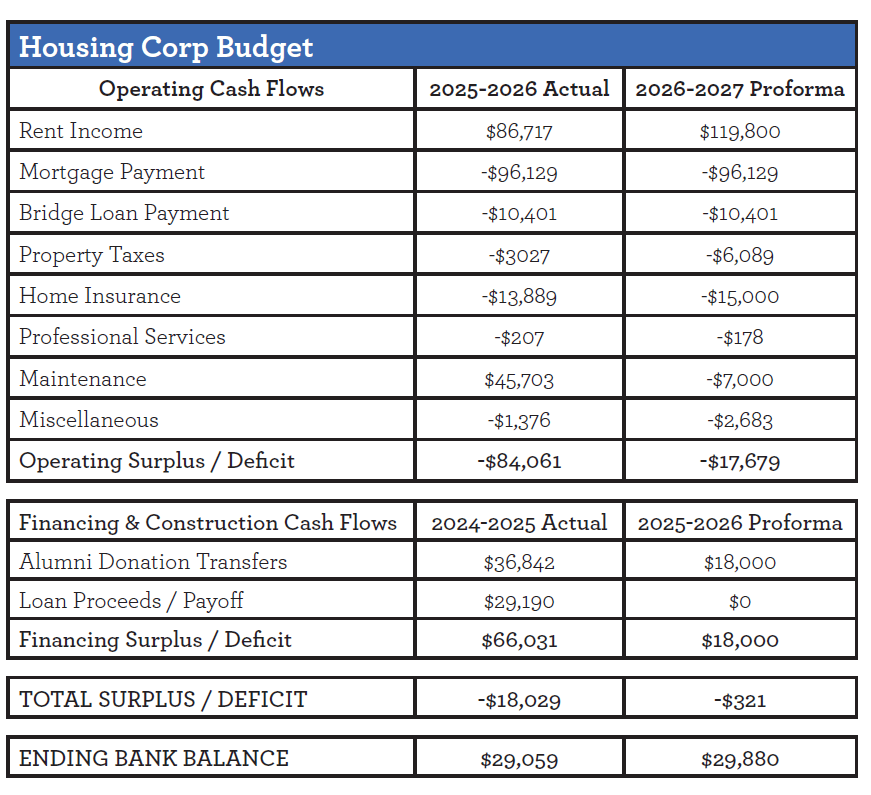
Additionally, below is a breakdown of the operating budget for 125 Chancellor Street for the past year, plus a pro-forma for the coming year. With the house expected to be fully occupied, our rental income should increase by 38%, from $86,717 to $119,800. Last year saw some outsized capital expenditures on repairs and improvements. Many of the repairs were the result of damage left by our prior tenant, and we secured a $29,190 settlement from them to offset most of it. Other improvements were related to unfinished items from the 2022-2023 renovation, which did not rise to our attention until our guys moved in. We expect the repair budget to be a much more modest $7,000 for the coming year, but this is a best guess. Despite our $2.3 million renovation, the east wing of the house is still 128 years old and full of surprises.
Even with the house at full occupancy, we are forecasting a roughly $18,000 operating deficit, which we should be able to offset with alumni donations. We expect we will always need some level of alumni support to maintain the house, so we appreciate your continued support.
Finally, and not included in the budget below, in July 2027 our current mortgage rate of 4.5% is due to reset. Current market rates suggest our reset rate would be considerably higher, so we will likely take this opportunity to refinance. By July 2027, our original $1.4 million loan should be amortized down to approximately $1.27 million. We also have a $130,000 interest only bridge loan that we would like to retire, and rolling that into a new loan would result in a new $1.4 million mortgage. While our overall debt load would be $130,000 lower following that refinance, if interest rates remain where they are today, our monthly debt service could still be $500-1,000 higher. There will also be origination costs. The Housing Corp will keep everyone informed as our discussions with lenders progress.